Home Viewing Checklist Before You Make an Offer
- What document may an agent require before a home viewing?
- Preapproval and buyer agreements answer different questions
- Read a written buyer agreement before the tour
- Use the viewing to create questions, not certainty
- Before the visit
- Start outside and read the site
- Test the layout against daily life
- Review systems without impersonating an inspector
- Separate the property from the staging
- Build the pre-offer document list
- Compare total ownership, not only the rooms
- Sources
What document may an agent require before a home viewing?
An agent may ask for two different kinds of documents before arranging a private home viewing. A mortgage preapproval letter—or proof of available funds for a cash purchase—can show that the proposed price is financially plausible. Separately, an agent subject to current National Association of Realtors MLS policy must have a written buyer agreement with a buyer before touring a home together. Neither document is a home offer, inspection, appraisal, or final loan approval.
The exact requirement depends on the agent’s role, brokerage and MLS rules, state law, the seller’s instructions, and the kind of viewing. Ask which document is requested, why, what information it contains, how long it applies, and whether a narrower form is available. Take any agreement or local legal question to a licensed attorney or appropriately licensed real-estate professional in the relevant jurisdiction before signing.
Preapproval and buyer agreements answer different questions
| Document | What it addresses | What it does not establish |
|---|---|---|
| Mortgage preapproval letter | A lender is tentatively willing to lend up to a stated amount, subject to assumptions and later verification | A guaranteed loan, final rate, property approval, insurance, appraisal result, or personal affordability |
| Proof of funds | Evidence requested for a proposed cash purchase or cash portion, with format set by the recipient and transaction | Title to the property, an accepted offer, or a reason to reveal unrelated account information |
| Written buyer agreement | The relationship between buyer and real-estate professional, including services and compensation terms | A mortgage approval, property-condition finding, or automatic commitment to buy a home |
| Seller disclosure or property record | Information about the property supplied or obtained under the applicable process | Independent verification or a substitute for inspection and specialist review |
The Consumer Financial Protection Bureau defines a preapproval letter as a lender’s tentative statement that it may lend up to a certain amount. The letter rests on assumptions and is not a guaranteed loan offer. CFPB also notes that lenders use “preapproval” and “prequalification” differently and that a letter may have an expiration date, typically 30 to 60 days. A seller frequently requests one before accepting an offer; requiring it before a viewing is a transaction or brokerage practice, not a universal federal rule.
Preapproval is a ceiling from a lender’s preliminary review, not a spending instruction. Set your own comfortable purchase and monthly-cost limits. A letter also does not commit you to that lender; compare actual Loan Estimates on consistent assumptions when you reach that stage.
Read a written buyer agreement before the tour
National Association of Realtors policy has required an MLS Participant “working with” a buyer to enter a written agreement before an in-person or live virtual home tour since August 17, 2024. NAR’s consumer guide says an unrepresented visitor attending an open house on their own does not need that agreement merely to enter the open house. State law can impose different or earlier duties, and people outside that policy may work under other rules.
Before signing, identify:
- the professional and brokerage covered;
- the services each side agrees to provide;
- whether the relationship is agency, non-agency, transaction brokerage, or another locally permitted form;
- the property, area, price range, or tour to which it applies;
- its start, end, termination, and any carryover terms;
- how compensation is calculated, when it could be owed, and what happens if a seller does not pay it;
- whether the arrangement is exclusive;
- how conflicts, dual representation, confidentiality, and disputes are addressed under local law.
Do not treat “standard form” as meaning “no consequences.” NAR says the permitted relationship and terms retain choice and optionality under state law. Ask for time to read the complete agreement, keep a copy, and get local legal advice when its obligations are unclear. Do not upload financial or transaction documents to this publication; use a verified secure channel supplied by the actual lender, brokerage, attorney, or closing professional.
Use the viewing to create questions, not certainty
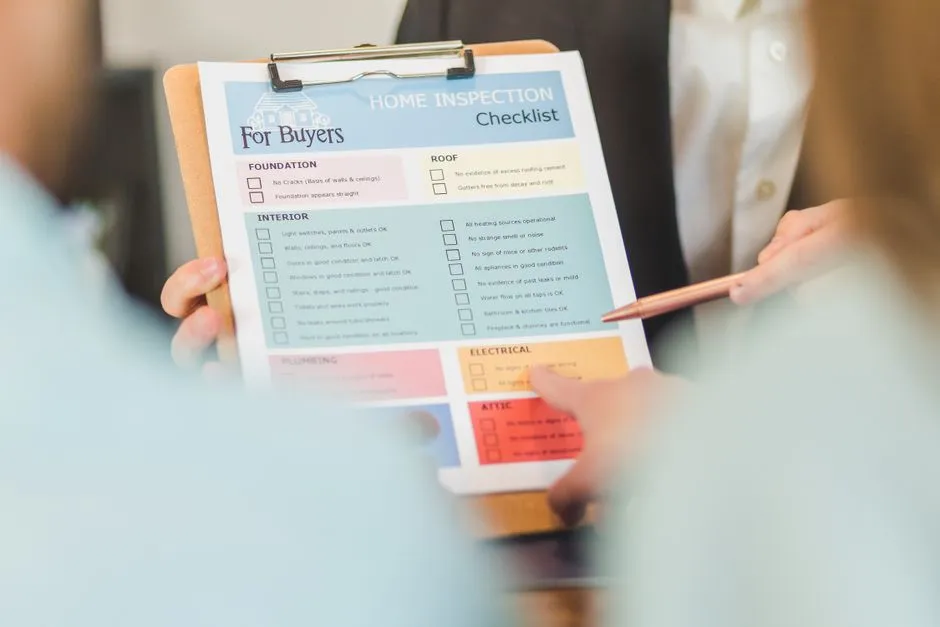
A home viewing checklist should help you record the building, site, systems, layout, surroundings, documents, and unresolved costs before making an offer. It does not replace a qualified inspection, appraisal, survey, title review, insurance quote, environmental testing, or legal advice.
Rules, disclosures, offer forms, contingencies, deadlines, and buyer remedies vary by location and transaction. Discuss the actual timing and contract language with an appropriately licensed local professional before signing. The tour produces an investigation list, not a certification.
Before the visit
Ask for the current listing, seller disclosures where provided, known repair records, utility information, association documents, property-tax information, and any prior reports the seller is permitted or required to share. Treat each item as a source to verify, not a warranty.
For most U.S. housing built before 1978, the Environmental Protection Agency says known lead-based-paint information and available records must be disclosed before the sale contract is signed, subject to the rule’s exemptions and exact scope. That federal disclosure does not prove that lead is present or absent, and it does not replace an appropriate inspection or risk assessment.
Map flood, wildfire, coastal, earthquake, industrial, noise, transport, and other hazards relevant to the area through current authoritative sources. Ask an insurer about eligibility and likely coverage for the exact address before the applicable contingency deadline. A mortgage preapproval does not promise that a particular property is insurable or affordable.
Bring a flashlight, phone camera, small level if useful, tape measure, outlet tester only if authorized and you know how to use it safely, and one checklist per property. Ask permission before opening panels, operating equipment, moving belongings, photographing personal items, or entering restricted spaces.
Start outside and read the site
Walk only where access is authorized. Note drainage direction, standing water, slope, retaining walls, visible foundation cracks, roof shape, damaged coverings, gutters, downspouts, exterior cladding, decks, steps, railings, trees, driveway condition, utility entry points, and neighboring land uses.
Look for additions, converted garages, finished outbuildings, or altered windows that may deserve permit and record checks. The absence of a permit sticker does not prove unapproved work, and fresh paint does not prove approval.
Observe traffic, aircraft, rail, commercial activity, odors, lighting, cell service, parking, and access at the actual time. Visit the public area again at another appropriate hour if the purchase advances. Never trespass on neighboring property to inspect a view or boundary.
Test the layout against daily life
Measure the rooms, doors, stairs, and storage that determine whether your furniture and mobility needs fit. Check sightlines, privacy, natural light, noise transfer, and the route from parking to kitchen. Confirm step-free access, bathroom usability, handrails, and circulation needs rather than trusting “accessible” as an undefined listing adjective.
Open cabinets and built-in storage only with permission. Note odors, stains, swelling, patched surfaces, condensation, peeling coatings, and floors that feel uneven. These are observations, not diagnoses. Record their location and ask what document or qualified person can resolve them.
Review systems without impersonating an inspector
Record the apparent type and visible condition of heating, cooling, water heating, electrical service, plumbing, well, septic, solar, fuel, ventilation, and major appliances. Ask for installation dates, permits, warranties, maintenance and service records, and ownership or lease status. Request actual usage records when available rather than relying on a hallway estimate.
Do not remove electrical covers, climb a roof, enter an unsafe crawlspace, test gas leaks with a flame, or operate unfamiliar equipment. Route electrical, gas, structural, roof, confined-space, and unfamiliar-equipment checks to qualified people following the relevant safety procedures. A brief tour cannot reveal every concealed defect or remaining service life.
HUD tells buyers that an appraisal is not a home inspection. Arrange an independent inspection appropriate to the property and location. Ask the inspector for a sample report and standards of practice, and consider specialists for structure, roof, sewer, septic, well, chimney, pests, pool, environmental hazards, or other concerns when the general inspector or property facts indicate they are needed.
Separate the property from the staging
Ask what is included in the sale: appliances, fixtures, window treatments, sheds, batteries, solar equipment, charging equipment, security systems, water treatment, fuel tanks, and rented devices. Put negotiated inclusions and exclusions in the contract. An item visible during a tour does not establish that it transfers with the property.
For condominiums, cooperatives, or planned communities, review current budgets, reserves, insurance, assessments, meeting minutes, rules, litigation, maintenance responsibility, rental restrictions, and approval processes with qualified advisers. Landscaping and a tidy lobby do not establish reserve adequacy or future assessment risk.
Build the pre-offer document list
Before an offer, identify what must be reviewed, when, and by whom:
- seller disclosures and material facts required locally;
- title commitment or report, exceptions, easements, liens, and restrictions;
- survey, boundary, encroachment, and access questions;
- permits, certificates, zoning, and legal use;
- property taxes and possible reassessment implications;
- insurance availability, exclusions, deductibles, and hazard requirements;
- inspection scope and contingency timing;
- financing, appraisal, sale-of-home, attorney-review, or other contingencies;
- association or shared-property documents;
- repair priorities and independent cost estimates.
Do not waive a protection solely because another buyer might. First understand the specific legal and financial consequence in the actual contract and jurisdiction.
Compare total ownership, not only the rooms
Add mortgage principal and interest, property tax, insurance, mortgage insurance if any, association charges, utilities, maintenance, immediate repairs, commuting, and reserves. Then use how to compare mortgage Loan Estimates on the financing side.
Browse property due diligence for the broader document workflow and mortgage paperwork for financing records. After the visit, label every note as observed, seller-stated, document-supported, professional opinion, or unresolved. That prevents a confident verbal comment from quietly becoming a fact in the purchase budget.
Sources
- Consumer Financial Protection Bureau, Get a preapproval letter — supports what a preapproval is, its tentative and assumption-dependent status, the typical 30-to-60-day expiry example, seller use, and the distinction from choosing a lender. Accessed September 4, 2026.
- National Association of Realtors, Written Buyer Agreements 101 — supports the August 17, 2024 MLS Participant policy, in-person and live-virtual tour scope, and negotiable relationship terms subject to state law. Accessed September 4, 2026.
- National Association of Realtors, Consumer Guide to Open Houses and Written Agreements — supports the open-house and asking-about-services exceptions described here. Accessed September 4, 2026.
- HUD, For Your Protection: Get a Home Inspection — supports the appraisal-versus-inspection distinction, sample-report question, and possible specialist testing. Accessed September 4, 2026.
- U.S. Environmental Protection Agency, Lead-Based Paint Disclosure Rule — supports the expressly U.S. and mostly pre-1978 disclosure scope and its timing before contract. Accessed September 4, 2026.